Positioning political selling, disclosed 2026-10-02
Options put/call open interest 0.61, read 2026-11-01
Ethical passes the values gate
Price344.63 USD
Fair value261.83
Ethical score76.1/100
RatingOVERVALUED
Our investment reviews on this name
2026-10-11Read Accumulation341.07+1.0% to today ✓Markup gives way to Accumulation first Accumulation read since July
2026-10-02Read Markup341.07+1.0% to today ✓Distribution gives way to Markup after a 10% rise in 5 weeks
2026-08-29Read Distribution311.30+10.7% to today Markup gives way to Distribution after a 7% slide in 4 weeks
2026-07-30Read Markup333.02+3.5% to today ✓Accumulation gives way to Markup after an 8% rise in 4 weeks
Our analytic regime reads on this name, dated and marked against the screened price. Small sample per name, and separate from the daily-framework accuracy on the Track Record page.
Every chart read we post on this name lands here. Each one says which way we lean, how firmly, and the line that would prove us wrong. When price settles a read, we add a new entry and say plainly how it went.
Entries are point-in-time and never edited. Times in UTC. Not advice.
31 Oct06:13 UTC
UpdateDaily chartHeld
Updates the daily read of 28 Oct, 09:35 UTC. Closes 343.83 to 348.91, high 351.43. No close under 338.70 or over 351.73. Results 2 Nov. See that read ↓
Update on Apple. Still open. It got to 351.43 on Thursday, a whisker under the 351.73 high, and closed Friday at 344.63. The 338.70 floor was never tested on a close. Results are due on 2 Nov, and those can gap through either level. A daily close over 351.73 is new high ground, a close under 338.70 opens 325.81. Which way does the report push it? Not financial advice.
28 Oct09:35 UTC
ReadDaily chartHeld
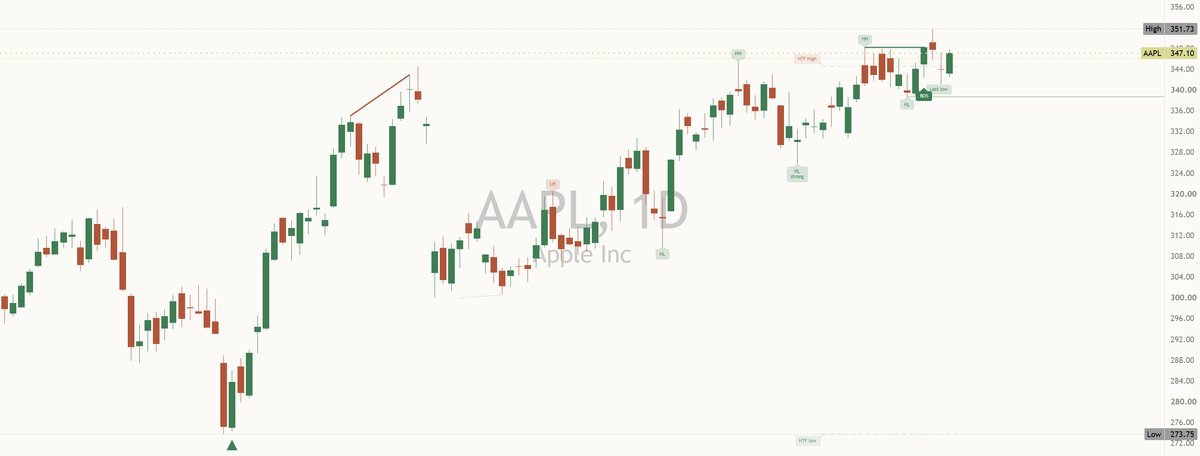
AAPL at 347.10 near its 351.73 high, can it clear it?
↑
Up · strong
Wrong if a daily close lands under 338.70.
23 Oct high351.73
Floor338.70
Next down325.81
Earnings2 Nov
AAPL closed Tuesday at 347.10, about 1.3% under its 351.73 high from 23 Oct, which is the 52-week high. It is over its 20-day (340.07), 50-day (331.06) and 200-day (295.28) averages, and the weekly chart has made higher highs and higher lows for most of the past two months. The low to protect is 338.70 from 20 Oct, the last pullback low.
Risk event: earnings are expected on 2 Nov (yfinance estimate, five days away). Earnings can gap through any level.
If it goes up (most likely). A daily close over 351.73 would be a new 52-week high with no old highs above it, so the next level is open space.
If it goes down (less likely). A daily close under 338.70 would break the last pullback low. Next is 325.81, the 1 Oct low.
If it chops. Price keeps moving between 338.70 and 351.73 into the results. Nothing to do in the middle. Let price come to the levels.
Does AAPL clear the high into earnings, or wait for the news first? Not financial advice.
Updated 31 Oct, 06:13 UTC: held. Closes 343.83 to 348.91, high 351.43. No close under 338.70 or over 351.73. Results 2 Nov. This entry stays as written.
Chart as posted, 28 Oct 09:35 UTC. Daily candles to the 27 Oct close.
25 Oct02:29 UTC
ReadDaily chartOpen
↑
Up · slight
Wrong if a daily close lands below 337.60.
Dip zone337.60 to 340.27
Out below333.86
First target348.15
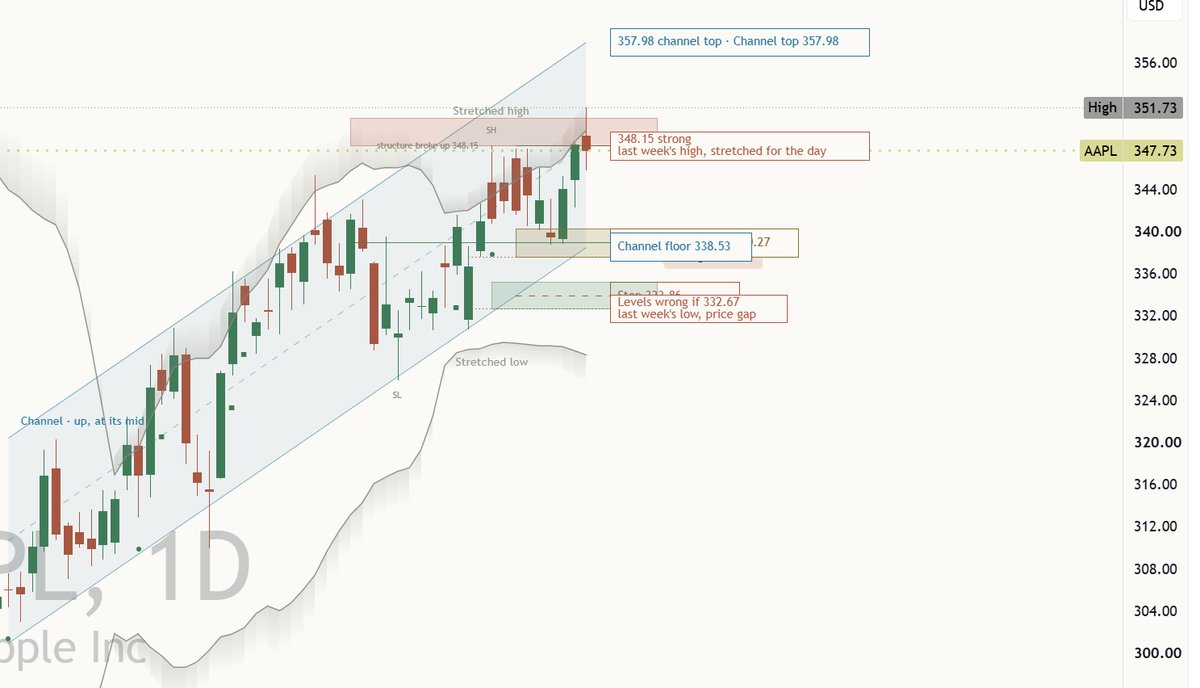
Apple is one of the few still holding up. Price is sitting on the 334 area with the weekly and monthly rising, even while the wider market leans lower. My plan: a long on a dip into 337.60 to 340.27, out below 333.86, first target 348.15. A daily close below 337.60 and I'd rather wait. Not advice.
Chart as posted, 25 Oct 02:29 UTC. Daily candles to the 23 Oct close.
A read stays open until price settles it. Held and Hit mean the line we named did its job. Wrong means it did not. Grey means nothing triggered.
Also posted on our social channels.
The full research record, in depth, below
The Label · The Season, Not the Day
This name holds its accumulation label.
Apple Inc. holds its Accumulation at $344.63. Consolidating, no directional conviction, held for 44 days.
As held on the ledger · 2026-10-30
Phase
Accumulation
Quantitative state
Consolidating, no directional conviction, held for 44 days
Price at the screen
$344.63
Valuation
40.01 trailing · 36.51 forward price to earnings
Values screen
PASS· score 76.1
Beta
1.07
The Workings
Five Screens, Shown in Full
Full pass across all five screens. This security clears the Titan Ethical Standard: its business and its balance sheet both stay inside the lines.
Test
Figure
Limit
What it means
Status
Business activity
Permissible
Core business clean
Its core business isn't built on prohibited lines: no gambling, alcohol, tobacco, weapons, or interest-based lending.
Pass
Debt load
27.46%
Below 33%
Interest-bearing debt is just 27.5% of its assets, well under the one-third ceiling: it does not run on borrowed money.
Pass
Interest-bearing cash
21.64%
Below 33%
Cash held in interest-bearing accounts and securities is 21.6% of assets, under the one-third limit.
Pass
Receivables
21.08%
Below 49%
Money owed to the company is 21.1% of assets, under the 49% limit.
Pass
Revenue purity
0.98%
Below 5%
Only 1.0% of revenue comes from non-compliant sources, under the 5% line.
Pass
Five checks adapted from AAOIFI screening standards: business activity plus four balance-sheet ratios. All five must pass for ethical clearance. Every figure is arithmetic on public accounts, not judgement.
The Ethical Read
Why It Clears, in Plain English
Apple clears all five screens. Its business is in a permissible area, its interest-bearing debt is about 27%, inside the ~33% line, and almost none of its income is interest, so it passes.
Read as at 2026-11-01. It updates when the underlying figures move, and past reads are kept below.
Follow this verdict
Get an email when AAPL's ethical verdict changes
Today AAPL passes the screen. If new figures move it to a fail, we send you one short email with the before and after. Verdicts change rarely, so you may not hear from us for a long time.
Free, no account needed. Every email has a link to stop.
The quantitative screen above is arithmetic and this name passes it. Separately, community boycott lists cite this company: Cited by BDS movement for operating significant R&D centres in Israel, including chip design facilities in Haifa and Herzliya. The desk records that flag here without folding it into the verdict: the screen measures the balance sheet, the overlay informs the conscience, and they are different judgements that belong to different owners. The second one is yours.
What the Numbers Say It Is Worth
The Fair Value Range
Our analysis reads OVERVALUED: it trades above our $261.83 fair value estimate, strong competitive moat, 16.40% revenue growth.
Fair value range in USD, drawn from the 2026-10-30 screen. The gold marker is the market price at the same screen. The price runs 24.0% above the base estimate.
Where our models see it going: fair-value estimate $261.83, with a range of $220.50 to $301.10, dated to the 2026-10-30 screen.
Fair value and rating are our own model estimates; the Street's range reflects third-party analyst estimates. Analysis, not advice.
The Business, in Plain Words
iPhone Giant's Market Valuation Overshadows Value
Imagine for a moment a world without iPhone - it's nearly impossible, right? That's Apple's influence. From smartphones and tablets to wearables and home accessories, the California tech giant has made itself indispensable to daily life, worldwide. The company's robust revenue growth of 16%, coupled with a profit margin of 28%, underpins its strong market presence and financial performance. Why it stands out is not just in its moat, but in its ability to consistently innovate and lead in consumer electronics.
However, despite Apple’s dominant position, the market is currently pricing AAPL at a significant premium. Our fair value sits at $260.41, which indicates the stock is overvalued by -16%. This high valuation, paired with a forward P/E of 32.6x, suggests that while the business is good, the price might not be. The consensus rating from 40 analysts may be a 'buy' with a median target of $335, but this doesn't change the fact that current valuations are lofty.
Risks for Apple are multifaceted. They include the cyclical nature of tech markets, potential regulatory challenges, and the ever-present competitive landscape. Given these factors, investors should consider whether the current price justifies the potential downside. Analysis, not advice.
Another profit measure, before interest, tax and non-cash costs: EBITDA.
The risks · The main risks here are ordinary market swings and the chance our fair-value read proves too optimistic.
Plain-English interpretation of our own screen data. Analysis, not advice.
Where & How to Trade
AAPL trades on a US exchange. As a listed security it is accessible through almost any international broker offering its home market. New to this, or investing from abroad? Our guide to accessing global markets covers brokers, currencies and the practical steps.
The Dated Journal · Newest First, Never Edited
Every Entry, As Written
2026-11-01Accumulation$344.63+0.0%Entry 24
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved down 0.0% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter. It reported earnings in this window, a natural checkpoint for the thesis.
2026-10-31Accumulation$344.63-1.2%Entry 23
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved down 1.2% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter. It reported earnings in this window, a natural checkpoint for the thesis.
2026-10-30Accumulation$348.91+1.5%Entry 22
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved up 1.5% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter. It reported earnings in this window, a natural checkpoint for the thesis.
2026-10-29Accumulation$343.83+0.5%Entry 21
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved up 0.5% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter. It reported earnings in this window, a natural checkpoint for the thesis.
2026-10-28Accumulation$342.00+0.0%Entry 20
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved down 0.0% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter. It reported earnings in this window, a natural checkpoint for the thesis.
2026-10-27Accumulation$342.00+0.0%Entry 19
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved down 0.0% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter. It reported earnings in this window, a natural checkpoint for the thesis.
2026-10-26Accumulation$342.00+0.0%Entry 18
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved down 0.0% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter. It reported earnings in this window, a natural checkpoint for the thesis.
2026-10-25Accumulation$342.00+0.0%Entry 17
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved down 0.0% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 17% above its long-term trend line with momentum reading neutral. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter.
2026-10-18Accumulation$342.00+0.3%Entry 16
The analysis reads accumulation. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved up 0.3% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it A, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter.
The framework has shifted from markup to accumulation since the last review. Smart money appears to be quietly building positions. This typically precedes a markup phase. Price has moved down 0.0% since our last review. Ethical screening: PASS with strong ethical credentials. The risk-adjusted return profile shows good risk-adjusted returns. Our composite framework grades it B, carrying a low risk profile. Technically it is holding around 18% above its long-term trend line with momentum reading overbought. Over the past year the shares are up 45%. Our forward projection puts the odds of a 10% gain over the next month near 23%. The street (43 analysts) rates it buy, with a mean price target of $309. Insiders have been net sellers over the past quarter.
Each entry above was written on its date, before the outcome. A journal you can prune is not a journal.