Volatility Regime Snapshot
Building on yesterday’s view from the Volatility Lens where the VIX closed at 14.87, today’s sharp 4.4 percent decline to 14.21 places the index below its five-day average of 14.81 and confirms a further compression in expected equity swings. This move leaves little room priced for immediate shocks, with the session range confined between 14.19 and 14.95. Market participants continue to treat equity exposure as low-risk, supported by the absence of defensive positioning in the options market. As our Positioning Pressure read notes, concentrated call buying in mega-cap names reinforces this stability and reduces the odds of sudden hedging flows. The result is a regime where volatility itself carries a lower cost, allowing positions to be held with smaller risk buffers than in elevated-VIX periods.
Term Structure and Curve Shape
The front end of the curve shows even stronger pricing of calm, with VIX9D at 12.13 sitting well below spot VIX. This steep upward slope signals that any volatility increase is expected to arrive gradually rather than through sudden spikes, which in turn lowers the cost of maintaining equity exposure and limits the incentive for protective hedging. VVIX at 83.2 reflects only moderate volatility of volatility, indicating that swings in the VIX itself remain contained. Such a configuration aligns with the one-sided call interest highlighted in Positioning Pressure, where institutions roll hedges into fresh upside strikes rather than buying downside protection. The curve therefore continues to favour carry strategies over defensive ones in the near term.
| Metric | Current Level | Tactical Insight |
|---|---|---|
| VIX Spot | 14.21 | Support near 14 limits downside in vol, yet any breach opens room for a quick retest of 15 resistance. |
| VIX9D | 12.13 | Deep discount to spot reduces near-term hedging demand and supports rolling short-dated structures. |
| VVIX | 83.2 | Moderate vol-of-vol keeps premium selling attractive while capping tail-risk repricing. |
Cross-Asset Positioning Context
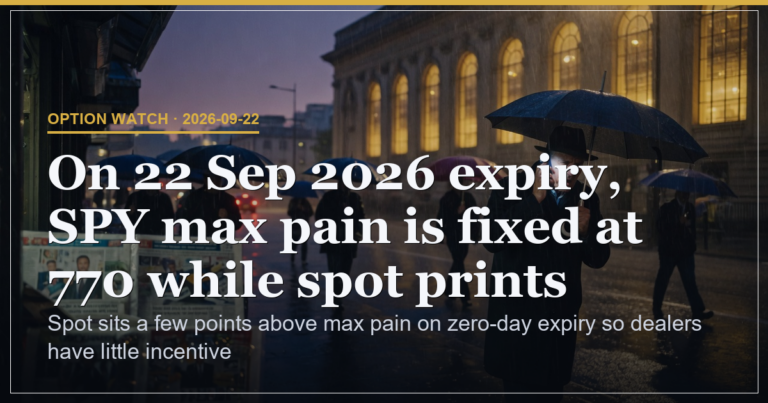
Positioning Pressure data shows call buying has taken clear control with the put-call ratio now at 0.45, pointing to institutions adding exposure through bullish structures rather than defensive put protection. This activity clusters tightly in eight mega-cap names, including AAPL, NVDA and TSLA, while broader market names register zero bearish prints. Spot trading a few points above max pain on zero-day expiry gives dealers little incentive to defend levels away from 770. The contrast with extreme retail bearishness noted in Sentiment Shift creates room for further upside if that fear begins to unwind. Every tick lower in the ratio adds weight to the call side and reduces the chance of immediate downside defence.
| Name | Flow Bias | Tactical Insight |
|---|---|---|
| AAPL | Call heavy | Institutions appear to be rolling hedges into fresh upside strikes, supporting near-term stability above 770. |
| NVDA | Call heavy | High gamma exposure here can amplify moves if spot holds and forces dealer re-hedging into the close. |
| TSLA | Call heavy | Concentrated bullish flow raises the probability of gamma squeezes on any positive catalyst. |
Scenario Probabilities and Risk Assessment
Three forward paths sum to 100 percent probability. Base case carries 55 percent odds that VIX remains pinned between 13.5 and 15.0 through month-end, consistent with the calm front curve and continued call dominance. Upside volatility scenario holds 25 percent probability if macro prints surprise or geopolitical headlines escalate, lifting VIX toward 18. Downside volatility scenario sits at 20 percent, where further compression below 13 would confirm an even lower-risk regime. Overall risk sits at 25 percent, driven primarily by the narrow breadth in tech leadership that could unwind quickly if rotation fails to broaden.
Experience-Level Guidance
Beginners should focus on monitoring the VIX level against the 14 support and 15 resistance markers, using any dip below 14 as a signal to reduce position size rather than add. Intermediate traders can overlay the term-structure discount to structure short-dated call spreads in the clustered names while keeping stop-losses tight around the 14.8 five-day average. Advanced desks may look to monetise the VVIX reading through relative-value trades between spot VIX and VIX9D, harvesting the steep carry while hedging the 25 percent tail risk with small out-of-the-money put wings. Across all levels the message remains the same: size positions to the prevailing low-vol regime rather than to historical averages.
Forward View and Bias
Low and falling VIX with a calm front curve points to continued market stability in the near term. This is analysis, not financial advice. Always manage your risk.