Macro Regime Snapshot
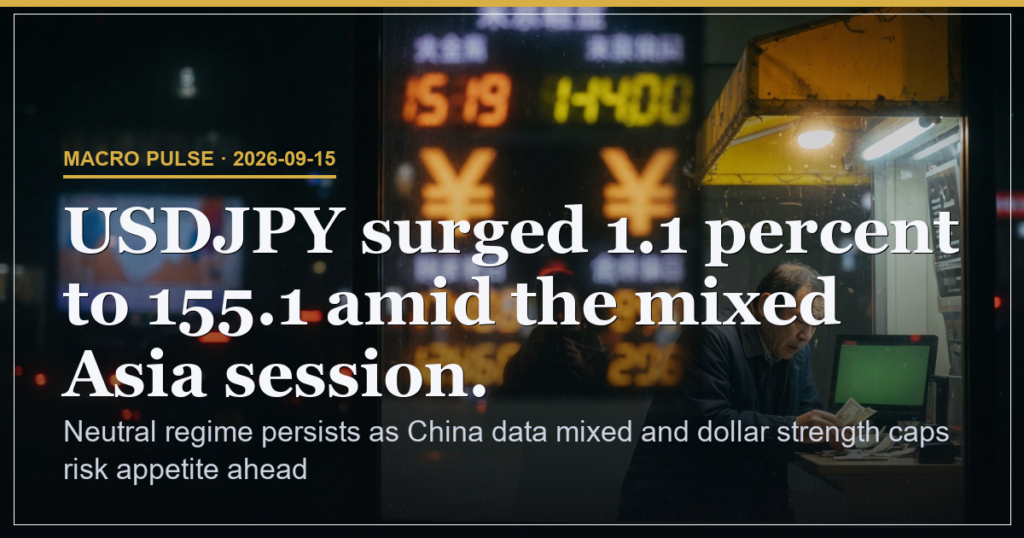
Neutral conditions persist with conviction anchored at moderate levels after the latest Asia releases. China industrial production surprised higher at 5.2 percent year on year yet retail sales and house prices fell short, leaving the recovery path fragmented. UK labour figures showed unemployment steady at 4.9 percent while earnings growth softened to 3.9 percent and claimant counts rose, limiting sterling upside. The dollar index advanced 0.35 percent to 99.5 as yen weakness accelerated, pushing USDJPY 1.1 percent higher to 155.1. These moves keep risk assets contained ahead of further global prints.
China Data Reveals Patchy Momentum
The mixed China print underscores an uneven expansion. Industrial output beat forecasts while fixed asset investment and retail sales disappointed, pointing to manufacturing resilience offset by weak consumer demand. House prices continued to contract at 3 percent, sustaining pressure on property sentiment. This combination caps any immediate bullish impulse for regional risk and reinforces the neutral macro stance.
UK Labour Data Caps Sterling Gains
UK releases delivered stability without acceleration. Unemployment held at 4.9 percent yet average earnings growth eased and claimant counts climbed sharply. The combination reduces the chance of near-term Bank of England hawkishness and leaves sterling range-bound against the stronger dollar. Cross-referencing the Positioning Pressure read, which notes bullish options flow in large caps outweighing absent dark pool prints, shows equity support remains selective and does not extend to sterling crosses.
Dollar Strength and Yen Weakness in Focus
Dollar index levels at 99.5 now act as a firm pivot. EURUSD tests 1.153 support while USDJPY clears 155 cleanly. Yen selling reflects broader risk-off flows in FX as highlighted in related pods. This dynamic tightens financial conditions for dollar-linked borrowers and keeps pressure on global risk appetite even as options positioning in tech names tilts higher into expiry.
Economic Calendar Implications for Risk
The session featured 24 releases with China and UK data dominating. Next prints centre on European wholesale prices and further inflation updates. Markets will watch whether the China output beat feeds through to commodity demand or whether softer retail figures weigh on growth expectations. The table below summarises key outcomes and tactical read-throughs.
| Release | Outcome vs Forecast | Tactical Insight |
|---|---|---|
| China Industrial Production YoY | Beat at 5.2 pct | Supports selective commodity exposure yet fails to lift broad risk given retail miss |
| UK Claimant Count Change | Rose to 27.8k | Caps sterling rallies and keeps GBPUSD biased toward 1.30 support tests |
| USDJPY Spot | Surge to 155.1 | Extends dollar strength and raises hedging costs for yen-funded carry trades |
Scenarios, Risk and Positioning Guidance
Three forward paths sum to 100 percent probability: base case of continued range trading at 55 percent, dollar-led risk compression at 25 percent, and China stimulus surprise lifting sentiment at 20 percent. Overall risk sits at 40 percent driven by the dollar strength factor that can amplify equity drawdowns if yen selling accelerates. Building on the Positioning Pressure read, bullish call flow in NVDA, META and peers provides a floor for large-cap indices but does not offset macro headwinds.
| Experience Level | Recommended Focus |
|---|---|
| Beginner | Track dollar index and USDJPY levels only, avoid leveraged crosses |
| Intermediate | Monitor China retail follow-through and sterling earnings revisions for entry timing |
| Advanced | Overlay options gamma from the Positioning Pressure flow with calendar events to size macro hedges |
Neutral bias prevails into the next data window. This is analysis, not financial advice. Always manage your risk.