Earnings Review · 06 August 2026
The print
Results are in but not yet verified against a primary source in our ledger; this review updates the moment the audited figures land. What does not change is our read below.
Give the business its due
The business itself is genuinely strong: revenue growing about 11%, net margins near 17%, a moderate competitive moat.
The valuation lens
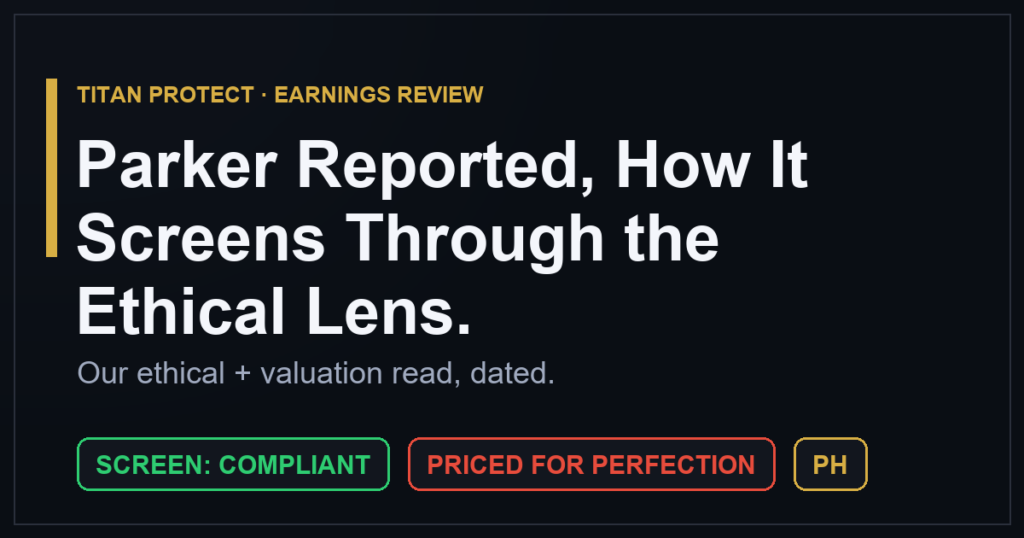
Our framework labels the valuation F. Fair value lands near $869 against a $997 share price, a margin of safety of about -13%. The trailing multiple sits around 37 times earnings, which only makes sense if the growth holds.
The ethical lens, our differentiator
Screens compliant (both standards). A name values-conscious investors can hold on the merits.
The compliant alternative
There is no direct compliant equivalent in the same industry on our screen, the honest answer is to screen a step wider rather than reach for a false substitute.
The verdict for a values-conscious investor
It clears the screen; size it to your own risk and conviction. We do not confuse a strong quarter with a suitable holding.
This is analysis, not financial advice. Always manage your risk.