For most UK Muslims, buying a home is the single biggest test of a riba-free life. A conventional mortgage is interest by design, so the question becomes: is there a genuinely Shariah-compliant way to buy, or is “Islamic mortgage” just clever marketing on the same product? The honest answer is that real alternatives exist, they work differently in ways that matter, and they come with trade-offs worth understanding before you commit. Here is how Islamic home finance actually works in the UK, clearly and without overselling it.
The Two Structures You’ll Meet
| Structure | How it works |
|---|---|
| Diminishing Musharaka (co-ownership) | You and the bank buy the home as partners. You live in it, pay rent on the bank’s share, and gradually buy that share out. As your ownership rises, the rent falls. Eventually you own it outright. |
| Ijara (lease-to-own) | The bank buys the property and leases it to you; your payments cover rent plus an agreed path to ownership, with the title transferring at the end. |
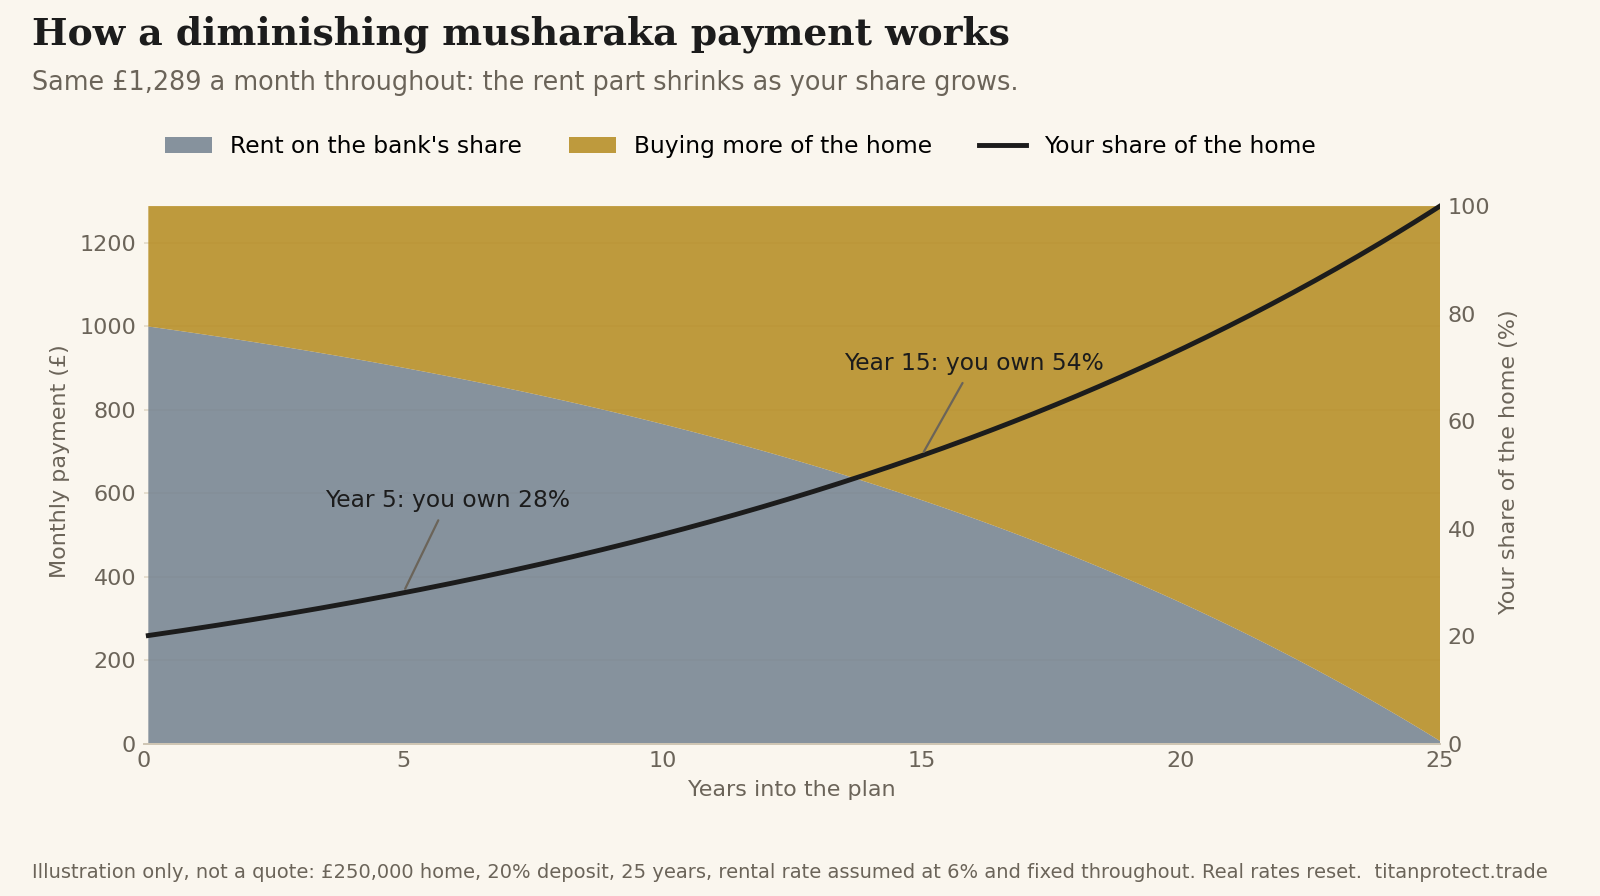
The key distinction from a conventional mortgage is real, not cosmetic: the bank actually buys and owns a share of the asset and earns a return through rent on a thing it owns, rather than lending you money and charging interest on the debt. That ownership of the asset, and the sharing of its risk, is what a Shariah scholar is looking for. It is why these products are structured, audited and signed off by a Shariah supervisory board, not simply relabelled.
The Honest Trade-Offs
This is where marketing stops and diligence starts. Islamic home finance in the UK is real, but it is not always cheaper, and it is not always simple. The monthly cost is usually set with reference to the Bank of England Base Rate (3.75% as of 18 October 2026, next decision 5 November), so it tends to land close to a conventional deal rather than far below it. The provider pool is small. For new UK customers, the established specialists are Gatehouse Bank and StrideUp; Al Rayan Bank, long the best-known name, now lists its home finance under its Premier banking service, so check whether you are eligible. Fewer providers means fewer products and sometimes larger deposit requirements. And the legal structure, while compliant, can involve extra steps. None of this makes it wrong; it makes it something to go into with eyes open. You are buying compliance and asset-sharing, and occasionally paying a small convenience cost for it.
Provider details checked 18 October 2026 against the providers’ own websites. Products and eligibility change often, so confirm with the provider before you apply.
The Honest Lens
Two cautions a values-first buyer should hold. First, “Islamic” on the tin is not the same as scholar-approved: confirm the specific product carries a credible Shariah board’s sign-off, not just the branding. Second, do not let the pursuit of the perfect structure push you into a home you cannot afford; taking on unaffordable payments is its own kind of harm. Compliance and prudence are meant to travel together. The goal is a home owned cleanly and sustainably, not a technicality won at the cost of financial strain.
The bottom line: a riba-free UK home purchase is genuinely achievable through diminishing musharaka or ijara with an established Islamic provider. The structures are real, asset-backed and scholar-supervised, not a rebrand of interest. Go in knowing the trade-offs: a smaller market, comparable (not always cheaper) cost, and a bit more legal structure. Compare providers, confirm the Shariah sign-off, and buy within your means. Faith and a family home are not in conflict; they just ask you to do the homework. Discipline over shortcuts, always.
Want the rates side by side? Our guide How to Approach a Mortgage in 2026 Britain compares conventional and Islamic pricing with dated figures, and Islamic Mortgage Structures Explained goes deeper on each contract.
This is educational analysis, not financial or religious advice. Confirm any product’s compliance with a qualified scholar and your own adviser. Facts and providers last checked 18 October 2026.