Titan Macro Desk · Monday 6 July 2026 · 12:15 London / 07:15 New York / 20:15 Tokyo
A note on timing: an overnight system failure took the desk offline between the Asian close and the London morning. This edition publishes late and covers the full overnight session plus the London morning, bridging into the New York handoff. The record stays honest, including about ourselves.
1. The Asian Session: A Quiet Verdict With One Loud Exception
The first Asian session after the jobs shock delivered less drama than the setup deserved. The Nikkei 225 closed flat at 69,738 despite the yen sliding to 162.20, which tells you Japanese equities have stopped converting currency weakness into gains at these heights. The ASX 200 eased 0.2% to 8,831 and Shanghai went nowhere at 4,041.
The exception was Hong Kong. The Hang Seng rose 1.0% to 23,589, the strongest major move of the night, with the China tech complex catching a bid as mainland flows returned after the US holiday. India kept its steady grind, the Nifty 50 adding 0.7% to 24,442.
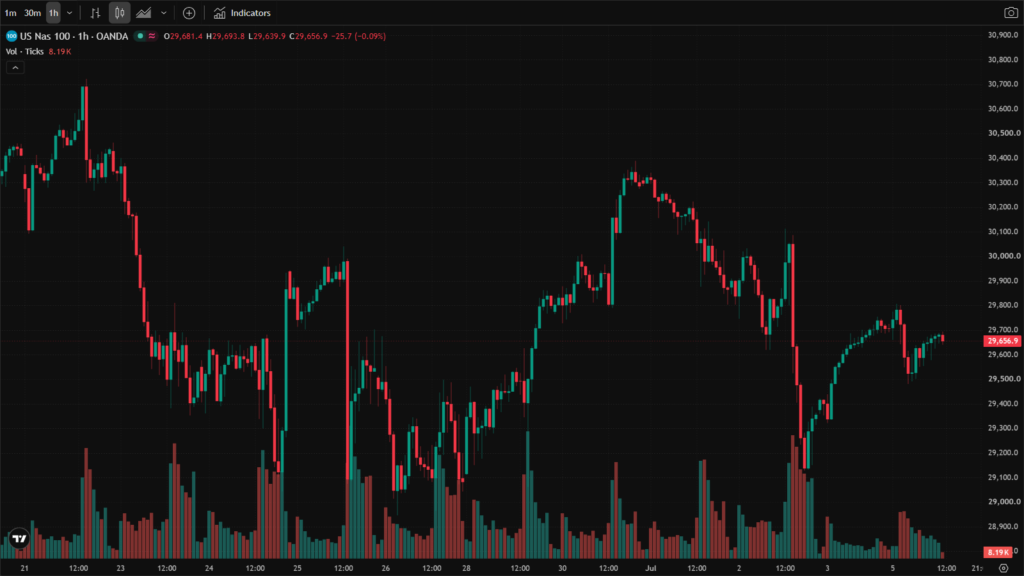
The real overnight story was in the futures market. NAS100 reopened roughly 1% above Thursday’s cash close, printing 29,667 by the London morning. The reopen crowd voted for the rate-cut reading of that 57K payrolls print, not the recession reading. Whether that vote survives Wednesday’s FOMC minutes is the week’s question.
2. Scoring the Weekend Map
The overnight outage means there was no Pre-Asia edition to score. The Weekend Edition carried the desk’s calls into the reopen, so that is the map we mark.
3. London at Midday, and the New York Handoff
Europe took the reopen in stride. The FTSE 100 trades 10,722, up 0.4%, the CAC 40 matches it at 8,542, and the DAX sits at 25,855, up 0.3% and consolidating last week’s 3.5% run as the continent’s leader. The Euro Stoxx 50 at 6,420 is quietly through its June highs.
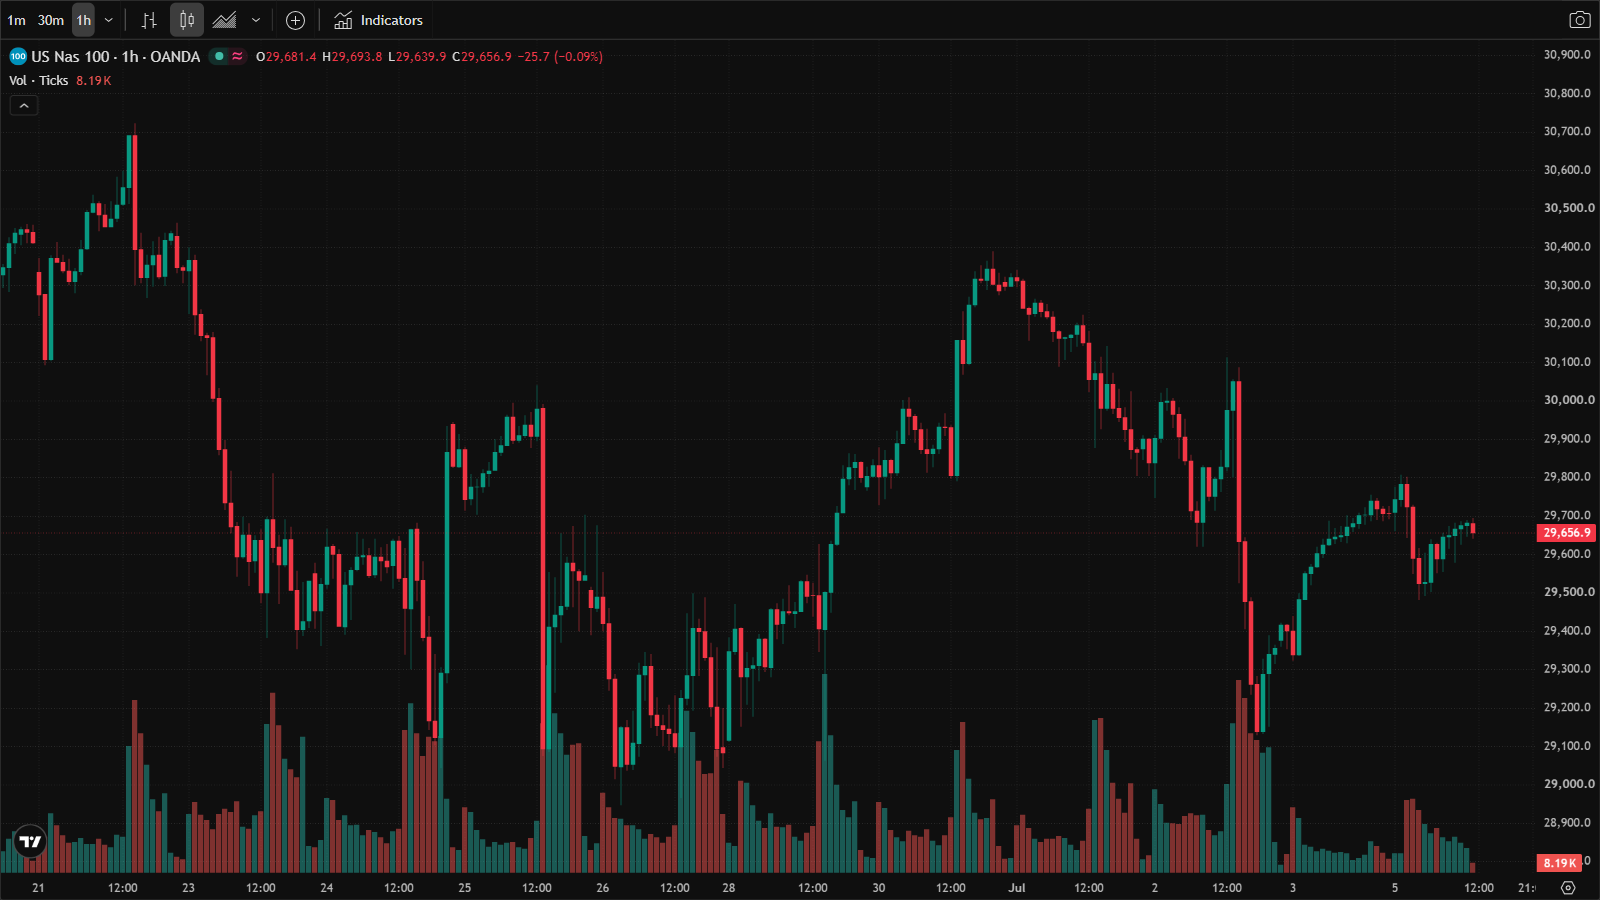
Two things matter for the afternoon. First, the volatility market is priced for a calm week: spot volatility near 16.4 while the nine-day measure sits near 12.4 says traders see nothing before Wednesday’s FOMC minutes worth paying for. That much complacency two sessions after a payrolls shock is itself a signal. Second, sentiment and price have split: one widely followed retail survey just recorded its largest single-week collapse in bullishness in years, while breadth quietly printed its strongest week of the summer. Bearish mouths, bullish hands. Historically that resolves upward more often than not.
Opportunity: the washout in stated sentiment against firm breadth is the kind of wall-of-worry setup that carries indices higher on light summer volume. As long as NAS100 holds above 29,355, dips remain for buying, not fearing.
Risk: the entire reopen gap rests on one interpretation of one data print. Wednesday’s minutes were written before the payrolls shock; a hawkish tone would collide with a market that has already spent the cuts. The 122-point gap back to 29,355 is the air pocket.
4. FX Focus
The dollar clawed back its round number: after breaking below 101 on the payrolls print, the Dollar Index reopened firmer at 101.01. That half-recovery is the FX market hedging its equity cousin’s conviction. EUR/USD held a tight 1.1421 to 1.1446 overnight range and sits at 1.1425; the pair needs the minutes, not the morning, to choose. GBP/USD trades 1.3345 after holding 1.3330, still digesting the cable strength that followed the cut repricing. EUR/GBP at 0.8561 keeps its slow drift.
The mover was USD/JPY, up 0.5% to 162.20. Yen weakness on a day the Nikkei closed flat breaks the usual transmission, and it revives the intervention conversation just as summer liquidity thins. AUD/USD at 0.6937 leans on the Hang Seng’s strength; it is the cleanest China-sentiment proxy on the board this week.
5. Key Levels for the Session
The Rest of the Board
The wider universe, one line each. Single names carry Thursday’s closes until New York reopens this afternoon; that session left stories worth knowing: Apple (AAPL) closed up 4.8% on its strongest day of the quarter, while Tesla (TSLA) fell 7.5% and Meta (META) lost 4.9%, so the index gap is arriving on top of a market that was already rotating hard beneath the surface. NVIDIA (NVDA) at 194.83, Microsoft (MSFT) at 390.49, Amazon (AMZN) at 242.67, Alphabet (GOOGL) at 359.91 and AMD (AMD) at 517.82 complete the big-eight picture.
6. The Calendar: A Slow Fuse to Wednesday
Monday is deliberately empty, which leaves price to trade positioning rather than news. The fuse burns toward midweek.
For a primer on why one jobs number rewired the whole week, the desk’s Complete Guide to Reading the Jobs Report is the reference.
7. Geopolitical Watch
Iran stays the unpriced tail. Diplomatic channels reopen this week after the funeral period, into the thinnest liquidity of the year; crude’s refusal to break $68 overnight says the energy market is not treating it as resolved. In Washington, early 2028 positioning stories are starting to move nothing but attention, which is itself worth knowing. The structural note: US equities now account for roughly 48% of global market capitalisation, a record. Concentration is a tailwind until the day it is the story.
8. Playing It: Three Time Horizons
Scalping (London afternoon into NY open): the DAX 25,780 to 25,900 micro-range is the cleanest rotation while the US pre-market digests. Fade the edges with 40-point stops, stand aside for the first 30 minutes after the New York open while the cash market votes on the gap.
Intraday: NAS100 in the 29,355 to 29,921 box. The high-probability trade is buying the first meaningful dip toward 29,450-29,520 with a stop below 29,340, targeting the 29,900 area. Shorts are counter-trend until 29,921 rejects on volume; do not anticipate that rejection.
Swing: two setups worth patience. A daily close above 29,921 opens 30,286 and confirms the rate-cut regime. In Gold, the broken $4,157 cap retested as support is the better entry than any chase; a hold there targets $4,290 with the stop below $4,128 at roughly 3.5 to 1.
Scenarios and Sizing
Position sizing: STANDARD on European indices and the NAS100 box trade. REDUCED on USD pairs until Wednesday’s minutes clear. AVOID chasing Gold at the highs; the retest is the trade. Overall risk appetite for the session sits around 60%: breadth and the sentiment washout support upside, but the unfilled gap and pre-minutes positioning cap conviction.
By Experience Level
Beginner: this is a week to watch one number and one level: Wednesday’s minutes and NAS100 29,921. If you trade at all, trade small in the index box with stops honoured mechanically. A reopen gap after shock data is exactly the environment where accounts get hurt doing too much.
Intermediate: the sentiment-versus-breadth split is your framework this week. Track whether dips get bought in the first hour of New York; that behaviour, repeated, is the confirmation the survey pessimism is fuel rather than warning. The Gold cap-retest is the cleanest single setup on the board.
Advanced: the volatility term structure is the mispricing candidate: nine-day vol near 12 into an FOMC minutes release, after a payrolls shock, with summer liquidity, is cheap event insurance by any historical measure. Structures that own Wednesday and sell the far end make sense here. Pair it with the USD/JPY intervention tail if you want the asymmetry.
Bias
The composite reading is constructive with a hard ceiling: buy weakness inside the 29,355 to 29,921 box, respect both edges, and let Wednesday’s minutes decide the regime. For the weekend’s full context, the Weekend Edition holds the map, and the Bitcoin Weekly Review covers the decoupling in depth.
This is analysis, not financial advice. Always manage your risk. Titan Macro Desk.
Watch this brief
More on the YouTube channel: new briefs daily. Subscribe so the next one reaches you.